PF due date extended for September 2026

As mentioned in our earlier post (PF limit enhanced) that EPFO vide its Circular dt 17-9-2026 enhanced the PF limit from Rs 15,000 to Rs 25,000. This change became effective from the date of publication, i.e. 17-9-2026.

As many of the employers were facing problems in execution of this change in the payroll records, the EPFO has now decided to extend the due date of filing of the Electronic Challan-cum-Return (ECR) and remittance of statutory EPF contributions for the wage month of September 2026 from 15 October 20206 (Due Date) to 31 October 2026.

Important:

This extension applies exclusively to the wage month of September 2026. It does not extend the statutory timelines for any other wage month or waive any other compliance obligations under the applicable law and schemes.
__
Socio Research & Reform Foundation (NGO)                       
512 A, Deepshikha, 8 Rajendra Place,
New Delhi – 110008
Posted in FCRA, TAX, LEGAL | Tagged , , , | Leave a comment

PF limit enhanced

Central Govt has enhanced the wage ceiling from Rs 15,000 to Rs 25,000 for covering employees under Provident Fund Coverage. So now all employees who receive salary (Basic+DA) upto Rs 25,000, now need to deduct PF @ 12%, which will be a maximum of upto Rs 3000. Employer’s contribution would also go up with an equal amount. The change has been brought by Notification No. SO 5109(E) dt 17-9-2026, effective from the same date.

Thus for employees whose, Basic + DA is above Rs 25,000, deduction would also be enhanced but would be limited to a maximum of Rs 25,000 limit of Basic + DA, i.e. @ Rs 3000/-.

To recap, effect after notification

  1. There is no change in contribution rate of 12%. 
  2. But the now the maximum deduction and employer’s contribution will be of Rs. 3,000/- each, instead of maximum of Rs. 1,800/- earlier.
  3. There is no change in wages base, it is same Basic + DA
  4. Employees with eligible PF wages between Rs. 15,001 and Rs. 25,000 who are not currently PF members will be covered effective 17 Sept’ 2026.

__
Socio Research & Reform Foundation (NGO)                       
512 A, Deepshikha, 8 Rajendra Place,
New Delhi – 110008

Posted in FCRA, TAX, LEGAL | 3 Comments

Can an Indian NGO transfer local donor funds to an NGO in Nepal for flood relief?

Hello

We are NGO registered under FCRA. Indian donor wants to donate to our NGO and wants us to send these funds to some NGO in Nepal for flood relief work. Do we have to comply with any regulations or we can directly transfer funds without any regulatory issues ? These funds are local Indian funds.

Surya Prakash Lunkar

Posted in FCRA, TAX, LEGAL | 6 Comments

Treatment of sale proceeds assets out of FCRA fund

Good Afternoon,

I seek your valuable advice for the following.

Old assets bought out of FCRA project in 2017 has been sold to ordinary local buyers in town. Where should we deposit the money/ cheque given by them?

Can cheque be deposited in either FCRA utility bank account or SBI MAIN Branch?

Anurita
Guwahati,
Assam, India

Posted in FCRA, TAX, LEGAL | 5 Comments

Latest Amendments in FCRA Rules & Forms – 3

These amendmentshave been brought to further tighten the rules and reporting Forms. The changes are applicable from the date of publication in the Gazette.

In earlier two posts, following topics have been covered:

  • Key Functionaries and applicability of FCRA towards For-Profit entities
  •  Project-wise disclosure of Purpose&GeographicalAreas where projects are being implemented

In today’s posts we cover issues relating to

  • Prohibiting foreign citizens as Board members / trustees, and
  • FC to be used in India only.

Eligibility of Foreign citizens as Key Functionaries

  • As a practice, FCRA Dept did not allow foreign citizens as Key Functionaries, though this was not specified anywhere in Act or Rules. FAQs did mention it, but considering FAQs do not have legal sanctity, the rule remained more of a practice and not a legislative provision.
  • For first time, FCRA Dept has made it part of FCRA Rules 2011. Explanation 1 under Rule 9(5), has made it quite clear, that foreign nationals, other those of Indian origin (i.e. OCI card holder), shall not be considered eligible for grant of FCRA registration.
  • However, the term used is ‘shall ordinarily not be considered eligible‘. This means, that scope exists for allowing such persons to be considered as key functionaries on case-to-case basis.

FC to be used for activities in India

  • Under the same Rule [i.e. 9(5)], it has been clarified that the Foreign Contribution (FC) shall be utilized only for activities carried out in India. However, it has been added that this contribution should be on such activities which are in accordance with the association’s stated objectives and for the purposes for which it has been received.
  • The term ‘activities carried out in India’ has created a number of doubts. Normally this term has been interpreted in accordance with S. 11(1) of Income Tax Act 1961, which states ‘…….to the extent to which such income is applied to such purposes in India….’. ‘Purposes’ has generally been interpreted as applied to objects, where benefit is received in India. Would activities carried out in India would mean that FC can be applied only for activities in India. For example, would NPO officials travelling abroad to attend meetings / make presentations, which ultimately help NPO create awareness about projects being implemented in India, would be treated as activities carried out outside India or would any activity which benefits Indian objectives would be considered as being carried out in India. This term is likely to cause a lot of heartburn as interpretations are likely to vary.

__
Socio Research & Reform Foundation (NGO)                       
512 A, Deepshikha, 8 Rajendra Place,
New Delhi – 110008

Posted in FCRA, TAX, LEGAL | 1 Comment

Latest Amendments in FCRA Rules & Forms – 2

This amendment has been brought to further tighten the rules and reporting Forms. The changes are applicable from the date of publication in the Gazette.

In yesterday’s post, topics of Key Functionaries and applicability of FCRA towards For-Profit entities were covered.

In today’s post, issue relating to Project-wise disclosure of Purpose & Geographical Areas where projects are being implemented is being covered.

Purpose

  • Govt has come out with a detailed schedule of 105 predefined categories covering Religious (16), Cultural (18), Economic (19), Educational (22), Social (30). A NPO desirous of registration under FCRA would need to select one or more of them in its application.
  • The purpose as selected in its application would be specified in the FCRA registration certificate. Even current FCRA registered entities would need to comply with this requirement, within oneyear.
  • In effect, above means, that if a NPO’s activities as covered in grants do not get covered within the purpose / activity specified in its registration certificate. It will need to apply for amendment. For this purpose, Govt has formulated a Form FC-6F. This will become quite an onerous responsibility, and in case delays are experienced as generally is the trend at FCRA, a major bottleneck.

Geographical Area

  • Similar to as mentioned under Purpose above, all NPOs would need to ensure that the State in which they plan to undertake activity is mentioned in their Registration Certificate.
  • A fee of Rs 300/- per state has been affixed for the same.

Consequences of above requirements

  • Concern is, would this become a basis for some form of objection or even penalty, if the state covered in the FCRA Registration certificate is not included in the byelaws of the NPO.
  • Please note ensuring geographical location in FCRA registered entity is important, since this information is also being sought in Annual Return (FC4), when Project-wise information (para 3(a)) and location of assets (para 3(ba)) & 3(bb)) is being asked for.
  • Proposed Rule 17B (3) gives right to Govt to reject or approve the application after undertaking such inquiry as it deems fit.
  • It is foreseen that this could become a basis of number of disputes and penal provisions by the Dept.

__
Socio Research & Reform Foundation (NGO)                       
512 A, Deepshikha, 8 Rajendra Place,
New Delhi – 110008

Posted in FCRA, TAX, LEGAL | 2 Comments

Latest Amendments in FCRA Rules  & Forms -1

This amendment has been brought to further tighten the rules and reporting Forms. The changes are applicable from the date of publication in the Gazette. Considering large number of amendments which impact several aspect of FCRA legislation, it is decided to cover various amendments through a series of posts. So please bear with us. In this post we cover impact of amendments on For-Proft entities.

Key Functionaries defined

  • A Key functionary has now been formally defined. It includes Board members, Trustees, Office bearers of governing body (covering Trust, Society, Trade Union, etc). However Chief Functionary is still not defined, although it is the person who signs all documents to be submitted to the FCRA Dept online. Whoever signs application for registration / prior permission automatically becomes Chief Functionary. Subsequent changes, if any are informed to the FCRA Dept formally through Form FC-6E.
  • Any other officer or person, by whatever name called, who has control over or responsibility for the management or affairs of such person. Thus, a CEO who is not a director or office bearer of an NPO would now be covered. Earlier say husband of a managing trustee, would largely run the organisation, without formally having a post. Now theoretically such a person would be covered by the definition of ‘Key Functionary’.
  • Important pointto note, while For-Profits were covered earlier too, but now definition specifically states that partners in a partnership, Karta of HUF, director in a company will be covered.

The above raises a very interesting point, are For-Profit entities covered under FCRA. Theoretically once the definition of ‘Person’ was introduced through FCRA 2010 Act, For-Profit entities got covered, however how many have heard a For-Profit entity getting FCRA registration. There have been several instances, where FCRA Dept has refused to give FCRA registration on the ground that the applicant is likely to make ‘personal gains’. In fact clause (vi) of S.12(4), says exactly the same and is one of the ground for refusal to granting registration certificate.

I believe emphasis on partners, directors ismainly to discourage NPOs to start incorporating For-Profit entities, to avoid FCRA registration process.

__
Socio Research & Reform Foundation (NGO)                       
512 A, Deepshikha, 8 Rajendra Place,
New Delhi – 110008

Posted in FCRA, TAX, LEGAL | 2 Comments

Subscriptions to ZCZP Bonds to be allowed as CSR

Ministry of Corporate Affairs (MCA) has added a new entry (Entry No. xiii) in Sch. VII of the Companies Act 2013, allowing ‘Subscriptions to Zero Coupon Zero Principal (ZCZP) instruments listed on Social Stock segment of various stock exchanges’[1].

[2]The above subscriptions are subjected to following conditions:

  • MCA has limited that maximum amount that a company can invest through ZCZP is 10% of the total CSR Expenditure for that FY.
  • The NPO can issue ZCZP Bonds for a project, which will not be for a period more than the three years plus year in which introduced.
  • At the end of the project, NPO would need to transfer any unspent amount to any of the Sch VII listed funds, thus no need to transfer back unspent funds to the company at the end of the Financial Year.
  • Company management is not responsible for giving UC for such a project, that means, subscription amount to such Bonds will be treated as CSR expenditure for reporting by the company.
  • Company management is not responsible for monitoring of such projects, presumably as SSE requires such NGOs to submit annual and project-end evaluation reports to SSE portal.

    For any further information on above topic, watch out for further post.
    __
    Socio Research & Reform Foundation (NGO)                       
    512 A, Deepshikha, 8 Rajendra Place,
    New Delhi – 110008

[1]GSR 416(E) dt 27-5-2026

[2]GSR 415(E) dt 27-5-2026

Posted in CSR / SSE | 1 Comment

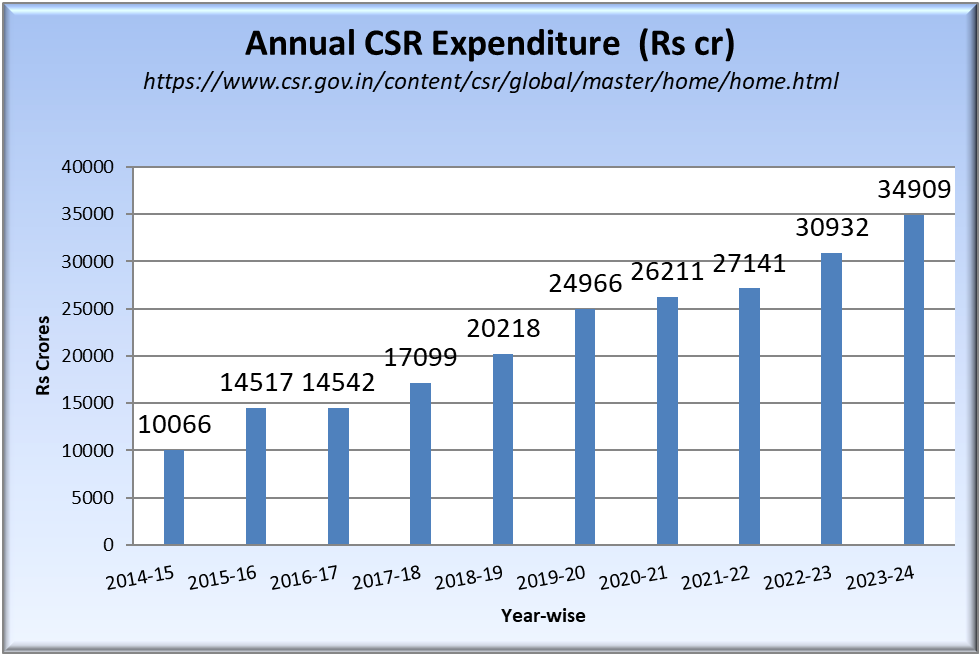
CSR spending during FY 2025

Listed companies CSR spending during FY 2025 rose by 23% to Rs 22,212 crores compared to Rs 18,011 crores during FY 2024 (source: Indian Express April 20).

Let’s not forget this data is only for listed companies as FY 2024 spending under CSR by all eligible companies was around Rs 35,000 crores. Main reason for increase in CSR is due to large increase in profits of listed companies (one estimate puts it around 22%).

It is noted that annual CSR spending has been increasing by around 27.4% at average annual growth since FY 2014-15, the first year of official CSR introduction.

__
Socio Research & Reform Foundation (NGO)                       
512 A, Deepshikha, 8 Rajendra Place,
New Delhi – 110008

Posted in CSR / SSE | 4 Comments

FCRA 2026 put on hold

FCRA amendment Act 2026, which was introduced by the Govt on 25 March 2026 in the Parliament. The bill puts in place mechanism of how Govt would takeover the assets and properties of all those entities whose FCRA has been cancelled.

Well now, the Sector can breathe easy, at least there is a temporary relief to these entities, as the Govt has decided to put the amendment bill on hold. The Govt sensing opposition parties getting together and launching major protests, has for the time decided to put the Bill on hold.

The data provided on FCRA website dashboard is indicative of how many NPOs could be impacted if the Bill becomes an Act. The following data is based on today’s data as available on FCRA website:

 Nos.%
NPOs Active under FCRA14,96529%
Registration cancelled21,97942%
Deemed Expired15,18029%
 52,124 

Based on above data, it is so alarming to note that the Govt could potentially take over the assets of 71% of all FCRA registered entities, which have at one time or other registered under FCRA. This would be almost a death knell for the survival of the Sector.

__

Socio Research & Reform Foundation (NGO)                       
512 A, Deepshikha, 8 Rajendra Place,
New Delhi – 110008

Posted in FCRA, TAX, LEGAL | 1 Comment